
Your vintage car isn’t just transportation-it’s an investment that appreciates over time. Standard auto insurance policies treat classics like regular vehicles, which means you’re likely underinsured.
At Central Ohio Insurance Services, Inc., we understand that vintage car insurance in Ohio requires specialized coverage designed for your specific needs. Let’s walk through why your classic deserves better protection.
Why Vintage Cars Command Special Insurance Treatment
Vintage cars appreciate in value rather than depreciate, which fundamentally changes how insurance should protect them. A 1967 Chevrolet Corvette worth $45,000 today might be worth $52,000 in three years if properly maintained, according to collector car market trends tracked by specialty insurers. Standard auto policies calculate payouts using depreciation schedules designed for vehicles that lose value monthly. This approach fails vintage owners because it ignores the reality that your classic car is gaining worth. When you file a total loss claim on a standard policy, the insurer applies depreciation formulas that were never meant for appreciating assets, leaving you significantly undercompensated.
Production Numbers Define Collectibility
Limited production runs define collectibility more than a vehicle’s age. A 1975 Pontiac Firebird produced in the hundreds of thousands differs fundamentally from a 1975 Ferrari 308 GT4 with fewer than 3,000 units built worldwide. Rarity drives value, and standard insurers don’t account for this reality when underwriting classics. Specialty insurers evaluate production numbers, original specifications, and whether your vehicle retains original components, because these factors directly determine replacement cost and market demand. Modified vehicles with custom work or rare original parts require even more precise valuation.
Restoration Projects Require Active Protection
Restoration projects sit in garages for months or years, yet standard policies either exclude coverage during work or treat the vehicle as non-operational. Classic car policies from specialized carriers protect vehicles under active restoration, safeguarding your investment while you rebuild engines, restore interiors, or source original parts. This coverage extends to parts stored separately and work in progress, addressing the reality that your classic may spend significant time in a restoration bay rather than on the road. Specialty insurers recognize that collectors invest substantial money and effort into these projects, and they structure policies to reflect that commitment.
Coverage That Matches Your Car’s True Value
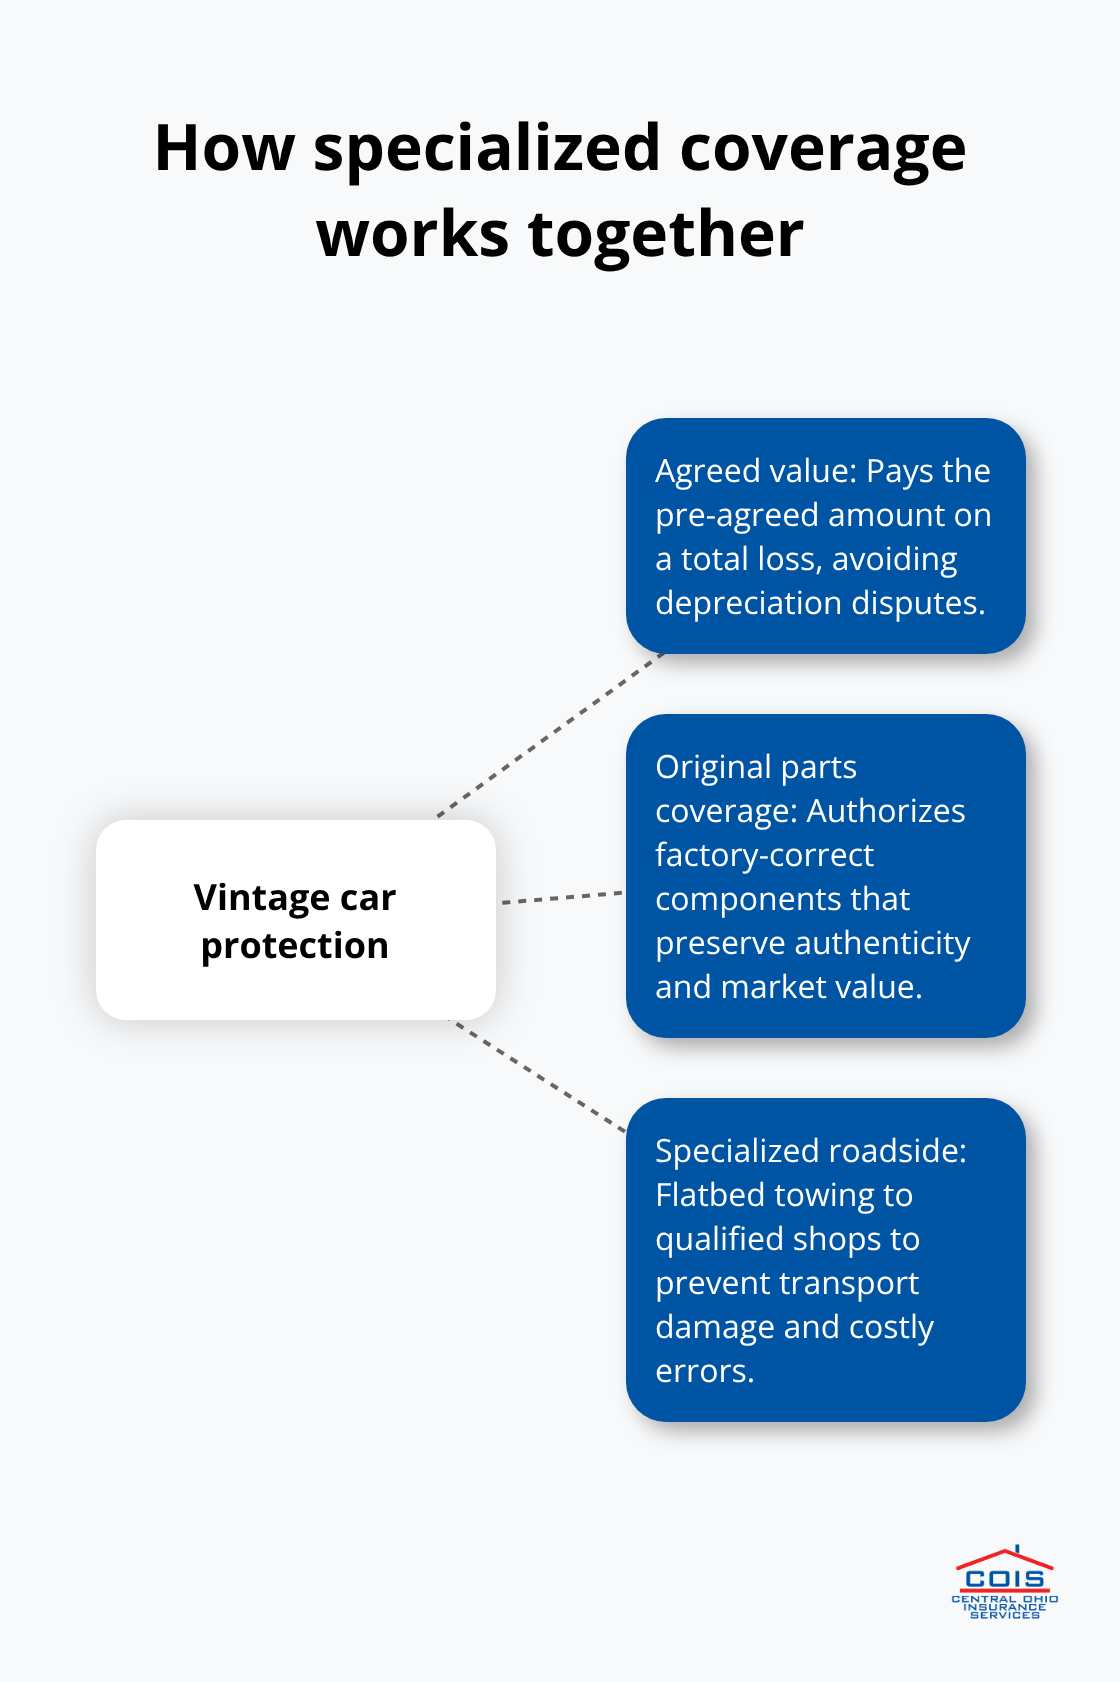
Standard depreciation formulas fail to capture what makes your vintage car valuable. Specialty carriers work with agreed value coverage, which means you and the insurer establish the vehicle’s worth upfront based on current market conditions, maintenance history, and any modifications (whether original or custom). This approach protects you from the gap between what a standard policy would pay and what your classic actually costs to replace. When total loss occurs, you receive the agreed-upon amount rather than a depreciated figure that undervalues your investment. This is why vintage car owners in Ohio need policies designed specifically for appreciating assets, not depreciating daily drivers.
What Coverage Options Actually Protect Your Vintage Investment
Agreed Value Coverage: Locking in Your Car’s True Worth
Agreed value coverage forms the foundation of proper vintage car protection in Ohio, and it’s the only valuation method that makes sense for appreciating assets. Unlike standard policies that pay depreciated actual cash value, agreed value locks in a specific amount you and the insurer establish upfront based on current market conditions, maintenance records, and any modifications. This means if your 1970 Dodge Charger is valued at $38,000 when you purchase the policy, that’s exactly what you’ll receive in a total loss claim minus your deductible-not some reduced figure calculated by depreciation tables designed for vehicles losing value.
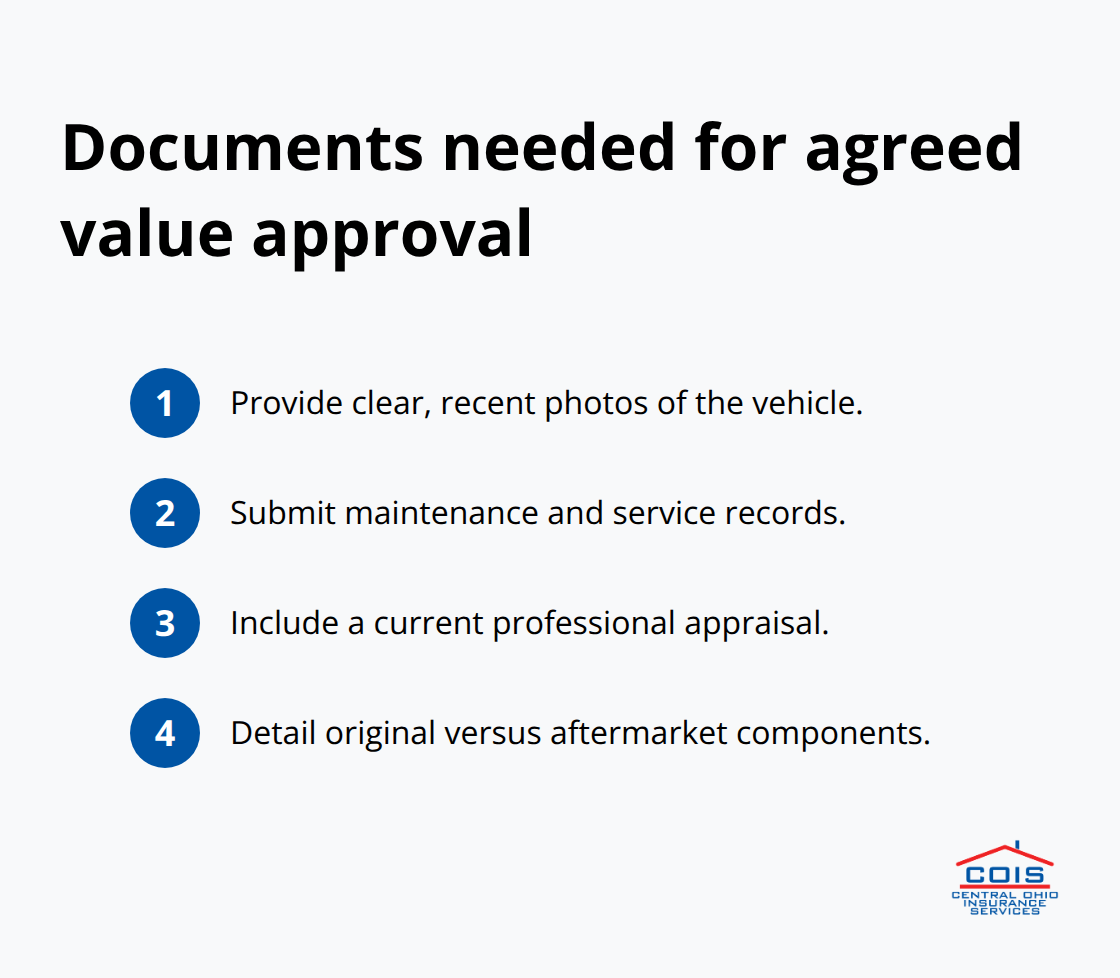
The process requires documentation: provide photos, maintenance records, recent appraisals, and details about original components versus aftermarket additions. American Collectors Insurance, rated 4.9 out of 5 stars by over 20,000 Ohio customers, structures their TreasureGuard policies around agreed value specifically because it protects collectors from undercompensation. When you file a claim, no negotiation about your car’s worth occurs-the agreement already exists.
This eliminates the financial devastation that occurs when a standard insurer offers $22,000 for a vehicle you’ve invested $38,000 to restore and maintain.
Original Parts Coverage: Preserving Authenticity and Value
Original parts coverage addresses a critical gap in standard policies: replacements use manufacturer-original components rather than aftermarket substitutes. When your classic car needs repairs, specialty carriers authorize shops to source and install original factory parts that preserve authenticity and value, whereas standard policies typically default to cheaper modern replacements that diminish collectibility. A 1967 Corvette with original Delco components commands significantly higher value than one fitted with modern equivalents.
This distinction matters because your vintage vehicle’s market value depends on maintaining its original character. Specialty insurers recognize that collectors invest in authenticity, not just transportation. They structure coverage to support that investment through access to original parts networks and repair shops experienced with vintage systems.
Specialized Roadside Assistance: Protection Beyond Basic Towing
Roadside assistance tailored for specialty vehicles goes beyond basic towing-carriers provide flatbed tow directly to qualified restoration shops rather than the nearest general repair facility, protecting your vintage investment from damage during transport. You also gain access to specialized repair networks familiar with classic vehicles, avoiding situations where a standard mechanic unfamiliar with vintage systems causes costly mistakes.
These coverage layers work together: agreed value protects your financial stake, original parts coverage preserves the vehicle’s authenticity and market value, and specialized roadside assistance keeps your classic safe from the moment something goes wrong. Ohio collectors benefit from policies that recognize your vehicle isn’t depreciating inventory-it’s an appreciating asset requiring protection matched to that reality. Understanding these options positions you to make informed decisions about which coverage components matter most for your specific vehicle and how you use it.
Why Standard Policies Fail Your Vintage Investment
Depreciation Formulas Destroy Vintage Car Payouts
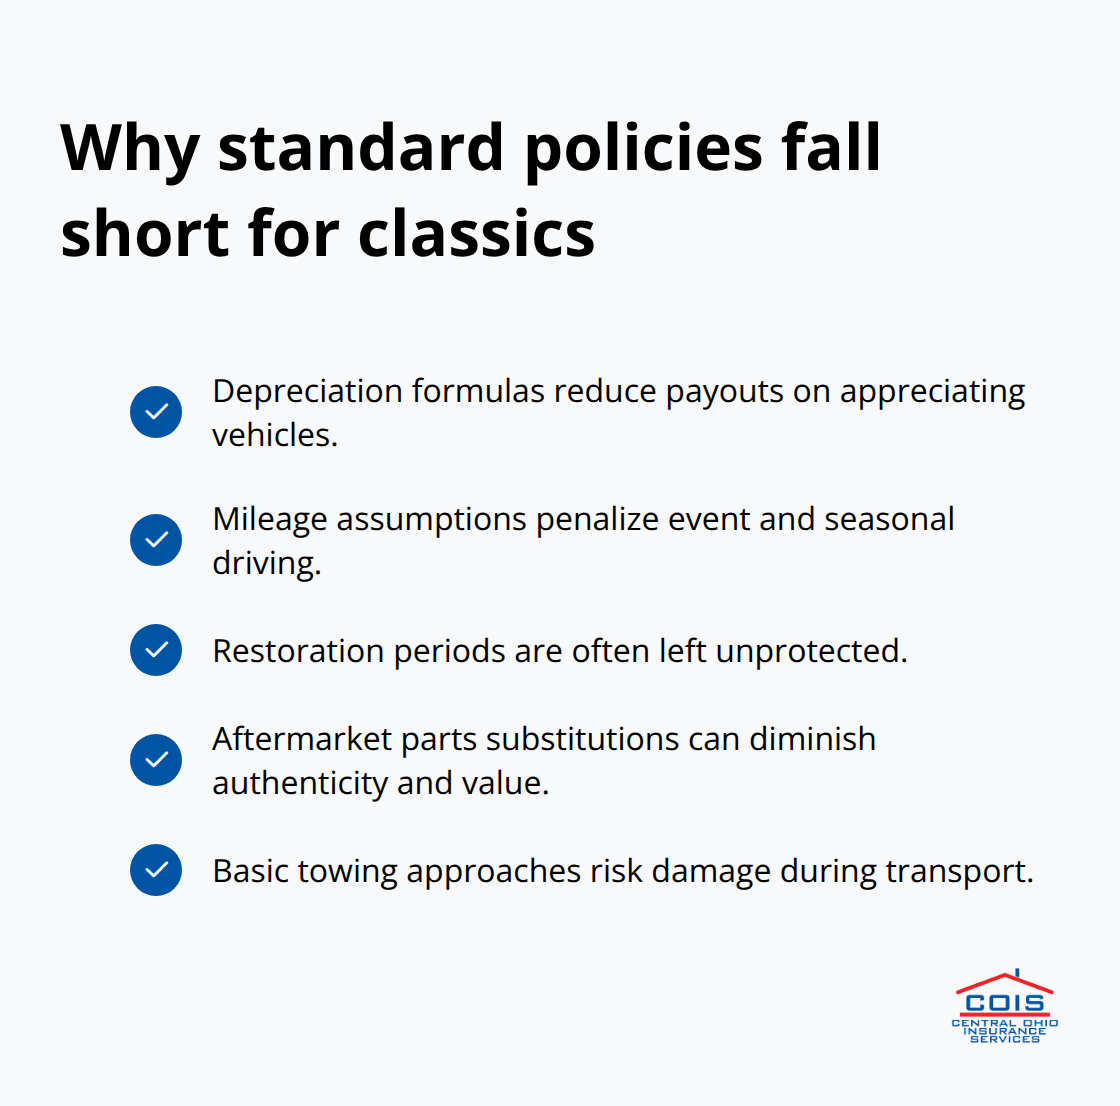
Standard auto insurance policies calculate claims payouts using depreciation formulas that assume your vehicle loses value every month you own it. This framework works for someone buying a 2024 Honda Civic, but it catastrophically fails vintage car owners. Classic cars tend to appreciate in value, yet a standard policy applies depreciation formulas that reduce your payout based on age rather than recognizing appreciation. When you file a total loss claim, the insurer subtracts depreciation from the vehicle’s assessed value, leaving you thousands of dollars short. A collector who invested $38,000 restoring a 1970 Dodge Charger might receive only $22,000 from a standard policy because the insurer calculated depreciation on a vehicle designed to lose value, not gain it. This gap between what you invested and what the policy pays represents real financial loss that specialty vintage coverage eliminates through agreed value protection.
Mileage Restrictions Penalize Collectors
Mileage restrictions on standard policies create problems for collectors who participate in shows, rallies, and casual weekend drives. Standard auto insurance typically assumes annual mileage around 12,000 to 15,000 miles, which works for commuters but not for vintage enthusiasts. When you drive your classic to a car show in Columbus, then a cruise night in Delaware, then a regional meet hours away, you quickly exceed the policy’s mileage expectations. Some standard carriers penalize high mileage with rate increases or coverage denial, while others simply fail to account for seasonal driving patterns common among collectors. Specialty vintage policies accommodate realistic mileage for collectors, recognizing that weekend cruises and event participation matter to how you use your vehicle.
Restoration Projects Sit Unprotected
Restoration projects create coverage gaps in standard policies because your vehicle sits inactive for extended periods while you source parts, rebuild components, or wait for shop availability. Standard insurers either exclude coverage during restoration or treat the vehicle as non-operational, leaving your investment unprotected during the months when you’ve invested the most money and effort into the project. Your classic car (whether it’s a muscle car, exotic, or hot rod) needs active protection while you work on it, not a policy that abandons you mid-restoration.
Final Thoughts
Your vintage car represents more than a financial investment-it reflects your passion for automotive history and craftsmanship. Standard auto insurance policies fundamentally misunderstand what makes classics valuable, applying depreciation logic to vehicles that appreciate over time. Agreed value coverage protects your actual financial stake, original parts coverage preserves authenticity that drives market value, and specialized roadside assistance keeps your classic safe from the moment trouble starts.
Vintage car insurance in Ohio requires more than generic coverage that treats your collector vehicle like a daily driver. We at Central Ohio Insurance Services, Inc. shop multiple carriers to find policies specifically designed for collectors like you, matching your vehicle with carriers that specialize in appreciating assets and structure coverage around how you actually use your car. Our licensed team understands production numbers, restoration projects, and the market realities that standard insurers overlook.
Contact Central Ohio Insurance Services, Inc. to discuss your classic car’s protection and receive fast quotes tailored to your specific vehicle. Our team provides clear guidance on coverage options and hands-on support when you need it, ensuring your vintage investment receives protection matched to its true value rather than depreciation formulas designed for daily drivers.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles and may contain inacuracies.